The rapid deployment of generative artificial intelligence, large language models, computer vision and intelligent automation is transforming demand for specialized semiconductor processors. AI chips are becoming essential infrastructure for organizations developing, training and deploying machine-learning systems across cloud computing, enterprise software, automotive platforms and edge devices.
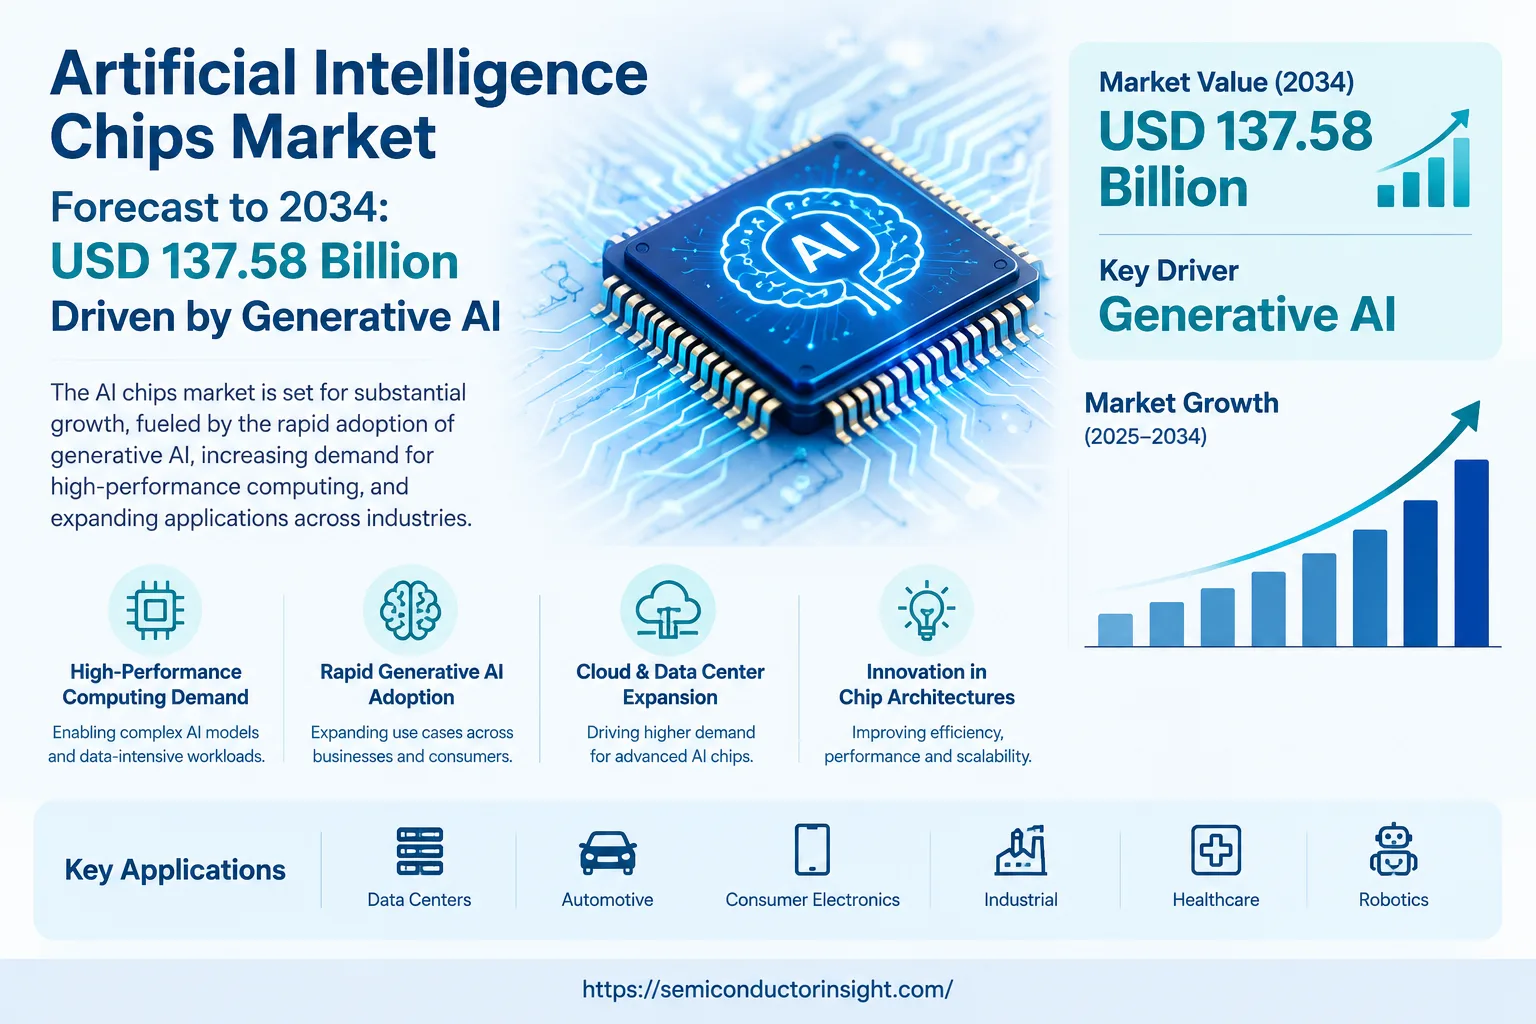
According to Semiconductor Insight, the global Artificial Intelligence (AI) Chips Market was valued at USD 10.081 billion in 2025 and is projected to reach USD 137.582 billion by 2034, expanding at a CAGR of 38.5% during the 2026–2034 forecast period. North America held the largest market position in the report's coverage, supported by accelerator design, hyperscale cloud procurement and advanced AI development.
AI chips include GPUs, application-specific integrated circuits, field-programmable gate arrays, neural-processing units and other processors designed to accelerate machine-learning workloads. Their commercial value depends on computational throughput, memory bandwidth, energy efficiency, software compatibility and total system cost.
Explore the complete Artificial Intelligence (AI) Chips Market analysis: https://semiconductorinsight.com/report/artificial-intelligence-ai-chips-market/
Why Is Demand for AI Chips Increasing?
AI models require substantial computational resources for training, fine-tuning and inference. Conventional processors remain important for general-purpose computing, but specialized accelerators can improve performance for parallel numerical operations and specific AI workloads.
Demand is also changing as inference becomes a larger part of commercial AI deployment. Organizations must process requests efficiently while balancing latency, power consumption and the cost of operating computing infrastructure.
Generative AI and Large Language Models Drive Accelerator Demand
Generative AI systems depend on large computational workloads and high-bandwidth memory access. GPUs and specialized AI accelerators are widely used to perform parallel calculations during model training and inference.
As models expand and enterprises introduce AI-assisted applications, data-center operators must evaluate processor performance alongside networking, cooling, memory and power requirements. These infrastructure dependencies influence procurement decisions and the pace of accelerator deployment.
Data Center Investment Supports High-Performance AI Computing
Cloud providers and enterprise data centers are investing in computing platforms designed for AI workloads. Accelerator modules, server systems and associated software create opportunities across the AI semiconductor supply chain.
The market is not determined solely by the number of processors shipped. Performance per watt, utilization, memory capacity, interconnect bandwidth and software optimization also influence the economics of deployed AI systems.
Custom ASICs and Neural Processing Units Expand the Technology Mix
GPUs remain important for flexible parallel computing, while custom ASICs can be designed for specific workloads and deployment environments. NPUs are increasingly relevant to on-device AI processing, and FPGAs offer reconfigurability for selected applications.
The appropriate architecture depends on workload characteristics, software requirements, power limits and expected deployment scale. Buyers increasingly evaluate complete platforms rather than processor specifications alone.
Edge AI Creates Opportunities Beyond the Data Center
AI processing is expanding into smartphones, vehicles, industrial equipment, cameras and connected devices. Edge AI can reduce dependence on cloud connectivity and enable lower-latency processing close to the data source.
This creates demand for processors that balance computing capability with limited power, thermal capacity and physical space. Automotive and industrial applications also require dependable operation and long qualification cycles.
Challenges Facing the AI Chips Market
AI chip development faces substantial design and manufacturing costs, advanced packaging constraints, memory-supply considerations and competition for semiconductor fabrication capacity. High power consumption and cooling requirements can also limit data-center expansion.
Software ecosystems remain important competitive factors. Developers need optimized libraries, frameworks, tools and support to make effective use of accelerator hardware. Supply-chain concentration and export restrictions can further affect market access and deployment strategies.
Artificial Intelligence Chips Market Segmentation
By Type
- GPU
- ASIC
- FPGA
- CPU
- NPU and Other Accelerators
By Application
- Cloud and Hyperscale Data Centers
- Enterprise and Sovereign AI
- Automotive and Industrial Systems
- Consumer Electronics and Intelligent Edge
By Workload
- Training
- Fine-Tuning
- Batch Inference
- Interactive and Reasoning Inference
- Edge Inference
By Deployment
- Merchant Accelerator Systems
- Custom Cloud Silicon
- Embedded Systems-on-Chip
- Accelerator-as-a-Service
By Component
- Processor Silicon
- Accelerator Modules and Cards
- Directly Associated Platform Software
Receive your Free Sample Report today: https://semiconductorinsight.com/download-sample-report/?product_id=39706
Regional Artificial Intelligence Chips Market Outlook
North America leads the report's regional coverage, supported by major AI platform developers, cloud infrastructure providers, accelerator design capabilities and substantial computing investment.
Asia Pacific plays a major role in semiconductor manufacturing, advanced packaging, electronics production and AI infrastructure deployment. Regional demand is influenced by domestic cloud investment and the expansion of intelligent devices.
Europe presents opportunities through industrial AI, automotive computing, research and enterprise adoption.
South America offers emerging demand through cloud services, digital transformation and enterprise AI applications. The Middle East and Africa may benefit from data-center investment, sovereign AI initiatives and digital infrastructure development.
Competitive Landscape and Key Companies
The report covers companies including:
- Advanced Micro Devices (AMD)
- Intel
- NVIDIA
- IBM
- Apple
- Qualcomm
- Samsung Electronics
- NXP Semiconductors
- Broadcom
- Huawei
- Amazon Web Services
- Microsoft
Competition extends across processor architecture, memory integration, interconnects, software ecosystems, energy efficiency and access to manufacturing capacity.
What Does the Artificial Intelligence Chips Market Report Cover?
The study examines market size, revenue forecasts, processor architectures, AI workloads, deployment models, end-use applications, regional demand and competitive developments. It also evaluates market drivers, restraints, technological innovation and opportunities across the AI semiconductor ecosystem.
Key Questions Answered by the Study
- What is the AI Chips Market size in 2025?
- What is the projected market value by 2034?
- What CAGR is expected during 2026–2034?
- How are generative AI and large language models influencing demand?
- What roles do GPUs, ASICs, FPGAs and NPUs perform?
- How are AI accelerators used in cloud data centers?
- Why is inference becoming important for processor design?
- What opportunities are emerging in edge AI?
- How do power consumption and memory bandwidth affect adoption?
- Which companies are covered in the competitive landscape?
Explore the full Artificial Intelligence Chips Market forecast and competitive analysis: https://semiconductorinsight.com/report/artificial-intelligence-ai-chips-market/
Get a Sample Report copy for free: https://semiconductorinsight.com/download-sample-report/?product_id=39706
EXPLORE MORE LATEST REPORTS :
Semiconductor Etch Equipment Market
High Power Silicon Photonics (SiPh) Chip Market
About Semiconductor Insight
Semiconductor Insight is a leading provider of market intelligence and strategic consulting for the global semiconductor and high‑technology industries. Our in-depth reports and analysis offer actionable insights to help businesses navigate complex market dynamics, identify growth opportunities, and make informed decisions. We are committed to delivering high‑quality, data‑driven research to our clients worldwide.
🌐 Website: https://semiconductorinsight.com/
📞 Asia Number: +91 8087 99 2013
🔗 LinkedIn: Follow Us