Balance sheet work is easy to underestimate. The report may look like a simple list of assets, liabilities, and equity, but each line depends on transactions being recorded correctly and placed in the right period. When bookkeeping is incomplete, the balance sheet can make a business appear healthier or less stable than it really is.
For businesses in Cleveland, online bookkeeping can provide a structured way to keep financial records current without building every accounting function internally. The work still requires attention to detail. Bank activity, accounts receivable, accounts payable, payroll, loans, fixed assets, and owner or shareholder activity all affect the final report.
Balance Sheet Work and Accuracy in Cleveland
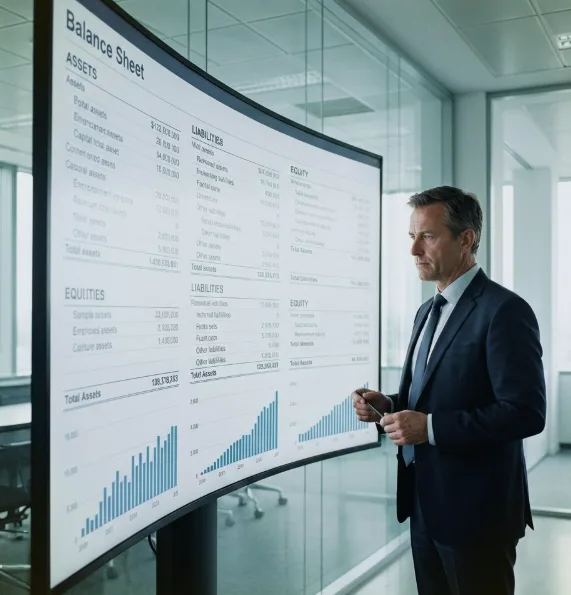
A balance sheet should be more than a document prepared at the end of a reporting period. It should help business owners and finance teams understand what the company owns, what it owes, and how much equity remains after those obligations are considered.
That starts with consistent bookkeeping. Transactions need to be coded properly, reconciliations need to be completed, and unusual balances need to be reviewed. If an account has been left unreconciled or a payment has been posted to the wrong category, the issue can carry into management reporting, tax work, and financial planning.
Finalert provides accounting and advisory services to U.S. businesses, including online bookkeeping in Cleveland. Its balance sheet services include detailed balance sheet preparation intended to help keep business finances accurate. Bookkeeping Services in Cleveland can fit businesses that need support with recurring bookkeeping and financial reporting processes.
The useful part of this approach is the connection between routine records and broader financial decisions. A clean balance sheet can support conversations about cash needs, outstanding obligations, working capital, and the reliability of internal reports. It can also make it easier to identify accounts that need further review before management or external parties rely on the numbers.
What to Review Before Relying on a Balance Sheet
Before using a balance sheet for planning, it is worth checking whether the underlying accounts are current and supported. Bank and credit card accounts should be reconciled. Accounts receivable should reflect open customer balances, while accounts payable should show unpaid bills that still belong to the business.
Debt accounts may need to be compared with lender statements. Payroll liabilities should be reviewed for accuracy and timing. If the business owns equipment or other long-term assets, those balances may require depreciation and supporting records. Equity accounts also deserve attention, particularly when there have been distributions, contributions, or other owner transactions.
These checks do not replace accounting judgment, but they create a more dependable starting point. Finalert also provides related services such as financial reporting, payroll, tax, financial planning and analysis, management reporting, and CFO advisory support. The right combination depends on the company’s accounting processes and reporting needs.
A balance sheet becomes more useful when it is prepared consistently, reviewed carefully, and connected to the records behind each account.