Portfolio Monitoring is the ongoing process of tracking the financial health, repayment behavior, risk profile, and performance of borrowers or exposures after credit has been originated. While underwriting determines whether a customer should receive financing, portfolio monitoring helps lenders understand whether that decision remains appropriate over time.
For banks, NBFCs, fintech lenders, and other financial institutions, monitoring a portfolio is critical because borrower risk can change quickly. A business may experience declining revenue, increasing debt, delayed payments, management changes, regulatory issues, or adverse industry conditions after receiving credit.
Effective portfolio monitoring allows lenders to identify these changes early and take appropriate action before a potential problem becomes a major credit loss.
Why Is Portfolio Monitoring Important?
Credit risk does not end when a loan is approved. Borrowers operate in changing economic and business environments, making post-disbursement monitoring an essential part of credit risk management.
A strong monitoring framework helps financial institutions:
- Identify early warning signals before default
- Track repayment and delinquency trends
- Detect deterioration in borrower financial performance
- Manage concentration and sector-specific risks
- Prioritize accounts for closer review
- Improve collections and recovery strategies
- Support regulatory and internal risk requirements
- Make better portfolio-level lending decisions
For example, if several borrowers from the same industry begin showing declining cash flows and delayed repayments, a lender can investigate sector exposure and adjust its risk strategy before losses increase.
Key Elements of Portfolio Monitoring
1. Borrower and Financial Performance
Monitoring borrower performance involves reviewing indicators such as revenue, profitability, cash flow, leverage, liquidity, outstanding debt, and repayment capacity.
For business borrowers, changes in financial performance can provide an early indication of potential stress. A consistent decline in revenue combined with rising debt may require additional assessment even if repayments are currently on schedule.
2. Repayment and Credit Behavior
Payment behavior remains one of the most important monitoring indicators. Lenders can track overdue payments, days past due, missed instalments, utilization patterns, and changes in repayment behavior.
A borrower who moves from consistently timely payments to repeated delays may represent an emerging risk that requires attention.
3. Early Warning Signals
Early warning signals help lenders detect potential deterioration before a borrower reaches serious delinquency.
Signals may include:
- Significant changes in financial performance
- Increasing leverage
- Frequent payment delays
- Negative legal or regulatory developments
- Management or ownership changes
- Business closure or operational disruptions
- Adverse industry developments
- Sudden changes in banking or credit behavior
The value of these signals depends on how quickly they are identified and acted upon.
4. Industry and External Risk Monitoring
Borrower performance can be affected by factors outside the organization. Changes in commodity prices, interest rates, regulations, supply chains, market demand, or industry conditions can influence repayment capacity.
Portfolio monitoring should therefore combine internal borrower data with relevant external risk intelligence to create a more complete view of exposure.
How Technology Improves Portfolio Monitoring
Traditional monitoring can become difficult when lenders manage thousands or millions of accounts. Manual reviews may consume significant resources and make it harder to identify subtle changes across a large portfolio.
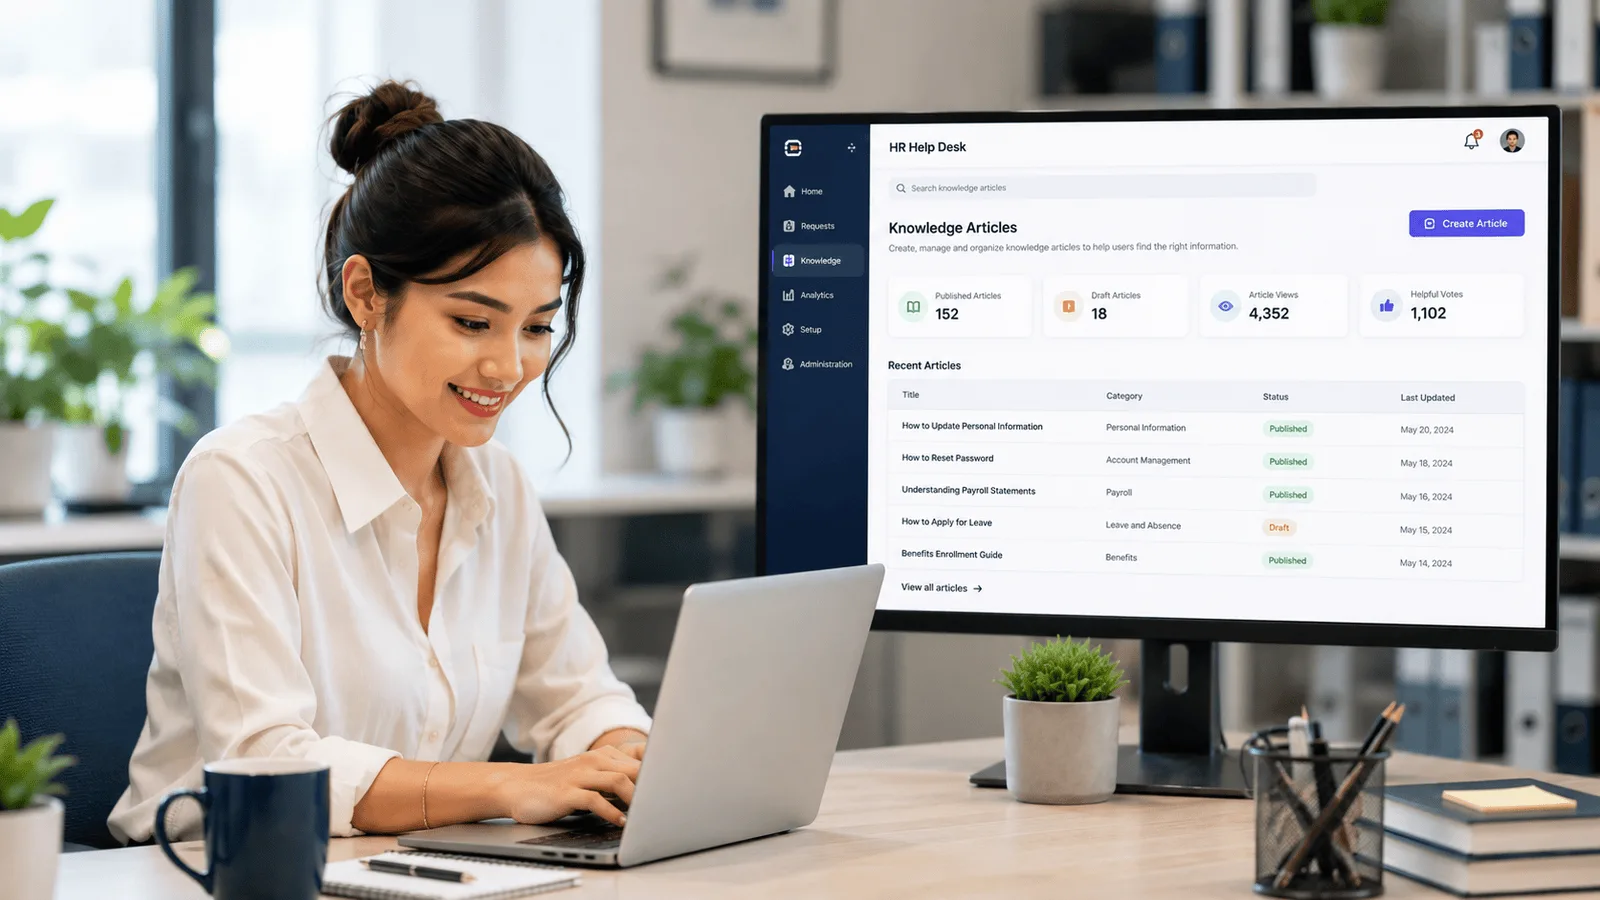
Modern portfolio monitoring platforms can automate data collection, risk indicators, alerts, portfolio segmentation, and reporting. Lenders can establish rules that trigger alerts when specific conditions are met.
For example, an NBFC could configure its monitoring system to flag an SME borrower when there is a combination of rising overdue amounts, declining financial performance, and negative external risk signals. The credit team can then investigate the account rather than manually reviewing every borrower at the same frequency.
This creates a more risk-based monitoring approach, where resources are concentrated on accounts that require attention.
Portfolio Monitoring for Banks and NBFCs
For banks and NBFCs, portfolio monitoring supports both individual borrower management and broader portfolio strategy.
At the borrower level, monitoring can help determine whether additional review, restructuring, enhanced documentation, or collection action is required.
At the portfolio level, institutions can analyze:
- Delinquency trends
- Product performance
- Geographic concentration
- Industry exposure
- Customer segments
- Vintage performance
- Risk-grade migration
- Non-performing asset trends
These insights can influence future underwriting policies, pricing, credit limits, provisioning strategies, and portfolio allocation.
Practical Example
Consider an NBFC with a large SME lending portfolio. One borrower initially demonstrates strong revenue and repayment capacity. Six months later, its revenue begins declining while outstanding debt increases and instalment payments become irregular.
A basic system may identify the borrower only after significant delinquency occurs. A robust Portfolio Monitoring framework can combine repayment data, financial indicators, and external risk signals to flag the account earlier.
The credit team can then conduct a focused review, understand the cause of deterioration, and decide whether to increase monitoring, adjust exposure, initiate collections, or take another appropriate action.
Best Practices for Effective Portfolio Monitoring
Financial institutions can strengthen monitoring by following a few practical principles:
- Define risk indicators clearly: Identify the financial, behavioral, and external signals that matter for each portfolio.
- Use risk-based segmentation: High-risk accounts should receive more frequent and detailed reviews.
- Automate routine monitoring: Technology can reduce manual effort and improve consistency.
- Combine multiple data sources: A single indicator rarely provides a complete risk picture.
- Set actionable alerts: Alerts should lead to defined investigation or escalation processes.
- Review monitoring rules regularly: Risk indicators should evolve with portfolio performance and market conditions.
- Connect monitoring with decision-making: Insights should influence underwriting, collections, pricing, and portfolio strategy.
Conclusion
Portfolio Monitoring is a critical component of modern credit risk management. It enables banks, NBFCs, fintech lenders, and other financial institutions to move beyond periodic reviews and develop a continuous understanding of borrower and portfolio risk.
The strongest monitoring strategies combine reliable data, early warning signals, automation, and informed human judgment. By identifying deterioration earlier and directing resources toward higher-risk exposures, financial institutions can improve operational efficiency, reduce potential losses, and make more informed lending decisions.
FAQs
What is Portfolio Monitoring in banking?
Portfolio Monitoring in banking is the continuous assessment of borrowers, loans, repayment behavior, financial performance, and other risk indicators after credit has been approved.
Why is Portfolio Monitoring important for NBFCs?
It helps NBFCs identify emerging borrower risk, monitor portfolio quality, prioritize high-risk accounts, improve collections, and support better credit risk decisions.
What are early warning signals in credit monitoring?
Early warning signals are indicators of potential borrower or portfolio deterioration, such as increasing delinquencies, declining financial performance, rising leverage, or adverse external developments.
How does technology improve Portfolio Monitoring?
Technology can automate data collection, risk scoring, alerts, portfolio segmentation, and reporting, allowing credit teams to identify important changes faster and manage large portfolios more efficiently.
How often should a loan portfolio be monitored?
The appropriate frequency depends on borrower risk, loan type, portfolio characteristics, and institutional policy. Higher-risk exposures generally require more frequent monitoring than lower-risk accounts.