You can buy a home before selling yours. Many Seattle homeowners face this exact problem every month. They find the right home, but their current one hasn't sold yet.
The good news is you have options. Some buyers cover the gap with a bridge loan, a home equity line of credit, or a cash-out refinance. Others make a contingent offer and hope the seller accepts the risk.
In Seattle's market, though, sellers often skip contingent offers. They pick buyers who can close fast with no conditions attached. That leaves many would-be buyers stuck on the sidelines, watching homes they love go to someone else.
This guide covers two paths forward. The first path is the traditional way. Homeowners use tools like bridge loans, home equity, and contingency offers to bridge the gap between homes. These methods work, but they come with real costs and risks.
The second path is newer. It's called the Contingency Buster Program. This program secures a guaranteed backup contract on your current home before you ever make an offer on the next one. That means your offer goes in clean, with no sell-first condition attached, and you compete like a cash buyer.
By the end of this guide, you'll know which option fits your equity, your timeline, and how much risk you're willing to carry. Let's start with the most basic question. Can you actually buy a home before selling yours?
Can You Buy a Home Before Selling Yours?

Yes, you can buy a home before selling yours. Thousands of homeowners do this every year, especially in fast-moving markets like Seattle.
The catch is timing. When you make an offer on a new home, sellers want certainty. They want to know the deal will close, and close on time. If your offer depends on selling your current home first, the seller sees extra risk in your offer.
That's called a home sale contingency. It tells the seller your purchase can only go through if your old home sells within a set window. In a slow market, sellers might accept that risk. In a competitive market like Seattle, they usually won't. They'll pick the buyer who can close without conditions, even if that offer is lower.
This puts homeowners in a tough spot. You want to buy your next home before you lose it to another buyer, but you don't want to be stuck owning two homes at once.
Here's the tradeoff in one sentence. Buying before you sell puts you in a stronger position to win the home you want, but you need a way to fund the down payment and closing costs before your current home's sale brings in cash.
That's the problem this guide solves. The next sections walk through your options, starting with the traditional ways homeowners cover that gap.
Ways to Buy a Home Before Selling
Homeowners use a few common methods to buy a home before selling their current one. Each method gives you funds or flexibility, but each comes with a cost. Here's how they work.
Borrow Against Your Home Equity
If you have equity in your current home, you can put it to work before you sell. This is one of the most common ways to fund a down payment on your next home. Most lenders want to see at least 15 to 20 percent equity before they'll let you borrow against it this way.
Home Equity Line of Credit (HELOC)
A HELOC lets you borrow against your home's equity as needed, like a credit card. You only pay interest on what you use. It's a flexible option if you aren’t sure exactly how much cash you'll need. The drawback is you still need to qualify based on your income and debt-to-income ratio, on top of your new mortgage.
Cash-Out Refinance
A cash-out refinance replaces your current mortgage with a bigger one and gives you the difference in cash. It can fund your down payment, but it also raises your monthly payment and often comes with new closing costs. This method also resets your loan term, which can mean paying interest longer overall.
Second mortgage
A second mortgage is a separate loan on top of your first one, using your home as collateral. It keeps your original mortgage rate in place, but it adds a second monthly payment. Because it's a separate loan, your debt-to-income ratio has to support both payments at once.
Use a Bridge Loan
A bridge loan is a short-term loan that covers the gap between buying your new home and selling your old one. Lenders base the loan on the equity in your current home. The drawback is cost. Bridge loans usually carry higher interest rates and fees than a standard mortgage, and you'll need to qualify for both loans at once. Most bridge loans also come due within six to twelve months, so you're on a strict timeline to sell.
Make a Home Sale Contingency Offer
A home sale contingency lets you make an offer that depends on selling your current home first. It protects you from owning two homes at once. The drawback is competitiveness. As covered earlier, sellers in a strong market often pass over contingent offers for cleaner ones. You can still write one if your agent advises it, but expect a smaller pool of interested sellers.
Other Ways to Cover the Gap
A few other options can help homeowners buy before they sell. Gift funds from family can cover part of your down payment. A 401(k) loan lets you borrow from your retirement savings, though you'll need to repay it on a set schedule. A sale-leaseback or rent-back agreement lets you sell your home but stay in it as a renter until you move. A non-QM loan is a flexible loan option for buyers who don't fit standard qualification rules, often at a higher rate. Each option adds its own set of rules and costs, so it helps to run the numbers with your lender before choosing one.
A Better Way to Buy a Home Before Selling: The Contingency Buster Program
Seattle's Mortgage Broker built a program that solves the problem in a different way. It's called the Contingency Buster Program, and it works by removing the sell-first condition from your offer completely.
Here's how. Instead of asking you to sell first or take on a bridge loan, the program secures a guaranteed backup purchase contract on your current home. That means a committed buyer is already lined up for your home before you ever write an offer on the next one.
With that backup contract in place, your next offer goes in clean. No home sale contingency. No hesitation from the seller. No reason for them to choose another buyer over you.
Here's what that unlocks for you.
Compete like a cash buyer
Your offer has no sell-first condition attached, so sellers treat it the same way they'd treat an all-cash offer. That puts you in a stronger position in a competitive market.
Your current home is already covered
Because you have a guaranteed backup purchase contract, you aren’t gambling on a future sale. You know your current home is handled before your next offer ever goes out.
Move once
You close on your new home and move straight in. There's no temporary housing, no storage unit, and no second move to plan around.
How the Contingency Buster Program Helps You Buy a Home Before Selling
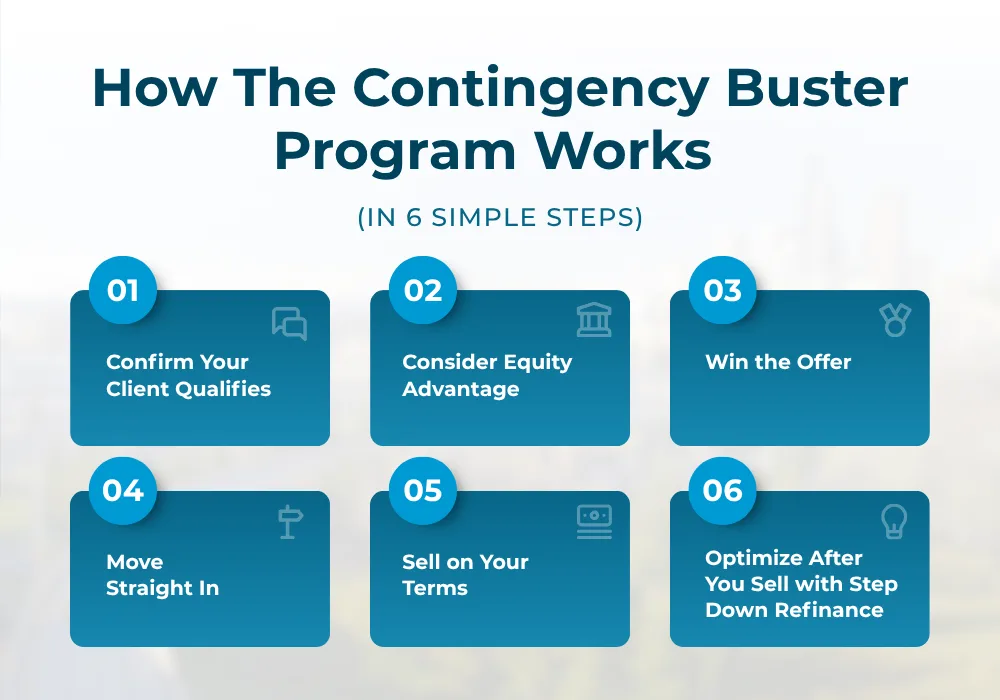
From your first conversation to moving day, the Contingency Buster Program follows a clear process. It covers six steps in total, from confirming you qualify to optimizing your mortgage after the sale. Here's exactly what it looks like, step by step.
Qualify and Power Up with Equity Advantage
To qualify, you need a minimum of 25 percent equity in your current home. That's the number that makes the sell-first condition disappear from your next offer entirely. This equity requirement exists because it's what allows Seattle's Mortgage Broker to guarantee the backup contract with confidence.
Once you qualify, you can choose to add Equity Advantage. This lets you put your home's equity to work before it sells, so your next offer is fully funded and ready to go.
Fund your down payment
Equity Advantage gives you access to up to 70 percent of your current home's equity before it sells. You don't have to wait for closing day to have the funds in hand.
Cover your costs
You can use the advance for renovations, staging, moving expenses, closing costs, or paying down debt to strengthen your qualifications. There are no restrictions on how you use the funds.
No monthly payments
Unlike a bridge loan, Equity Advantage carries no monthly payment. The advance gets repaid in full through escrow once your current home sells.
Win the Offer and Move In Once
With your offer fully funded and free of a home sale contingency, you can move on the home you want. Seattle's Mortgage Broker closes in as little as 10 days, which lets you compete directly with cash offers. Because your financing is already in place, you and your real estate agent can move the moment you find the right home, without waiting on a preapproval letter that depends on a future sale.
Once you close, you move straight into your new home. There's no juggling two closings or timing a sale around a purchase.
Sell on Your Terms, Then Optimize Your Mortgage
You can list your current home before or after your move, whichever makes more sense for your situation. Most clients choose to sell after they move, because it lets them stage and present the home without deadline pressure. A vacant, staged home sells for an average of 5 to 10 percent more than a comparable unstaged home. Without a closing deadline hanging over you, you and your agent can also price the home to attract stronger offers instead of the fastest one.
Once your home sells, any remaining equity can go toward your new mortgage through Seattle's Mortgage Broker's Step Down Refinance program. That lowers the principal balance on the home you just won.
How It Compares to a Contingent Offer or Bridge Loan
A contingent offer costs you certainty. Sellers see the risk and often choose another buyer instead. A bridge loan costs you money, since you're paying higher fees and qualifying for two loans at once. The Contingency Buster Program is built to avoid both tradeoffs. Your offer carries no sell-first condition, Equity Advantage carries no monthly payment, and the whole process moves fast enough to compete with cash. In short, a contingent offer trades certainty for a lower cost, a bridge loan trades cost for certainty, and the Contingency Buster Program is designed to give you both.
Which Option Is Right When You Buy a Home Before Selling?

When you buy a home before selling, the right choice depends on your equity, your market, and how much risk you're willing to carry.
If you have strong equity and want to avoid new debt or monthly payments, the Contingency Buster Program with Equity Advantage is likely your best fit. If your equity is lower, or you only need a small short-term boost, a HELOC or cash-out refinance might make more sense.
If you're buying in a slower market where sellers are more open to contingencies, a home sale contingency could work without much added risk. But in a competitive market like Seattle, a guaranteed backup contract puts you in a much stronger position.
Before you decide, avoid a few common mistakes. Don't assume every lender offers the same equity access or the same closing timeline. Don't wait until you've already lost an offer to look into your options. And don't skip getting preapproved, since that step shapes how strong your next offer can be.
The best move is to talk to a lender who can walk through your specific numbers with you. One conversation can tell you exactly what you qualify for and which path makes the most sense for your situation.
Ready to make a competitive offer on your next home? Reach out to Seattle's Mortgage Broker to see if you qualify for the Contingency Buster Program.
Frequently Asked Questions
Can You Buy a Home Before Selling Yours?
In most cases, yes. Lenders and specialty programs both make it possible, as long as you have enough equity or another way to fund your next down payment.
Is It Risky to Buy a Home Before Selling Yours?
It can be, if you rely on a contingent offer or take on a costly bridge loan. Programs that guarantee a backup buyer for your current home remove most of that risk, since you aren’t gambling on timing.
What Is a Home Sale Contingency, and Should You Use One?
It's a clause that ties your new home purchase to selling your old one first. It can protect you financially, but it often weakens your offer, so it's worth considering only in a slower market.
How Can You Make a Non-Contingent Offer Before Your House Sells?
You'll need funding lined up that doesn't depend on your old home's sale, whether that's equity you've accessed early or a guaranteed backup contract. That's what lets you drop the sell-first clause and compete like a cash buyer.
What Is a Buy-Before-You-Sell Program, and How Does It Work?
It's a service that secures your current home's sale in advance, so you can make a clean offer on your next one. The Contingency Buster Program, for example, lines up a guaranteed backup buyer and can even advance you equity before closing.