Small businesses often have a good idea of how much money they expect to make. The harder question is knowing when that money will actually be available.
A business might have strong sales but still struggle to cover payroll, vendor invoices, taxes, loan payments, or other expenses because customer payments arrive later than expected. This is where 13-Week Cash Flow Forecast Services can provide useful visibility.
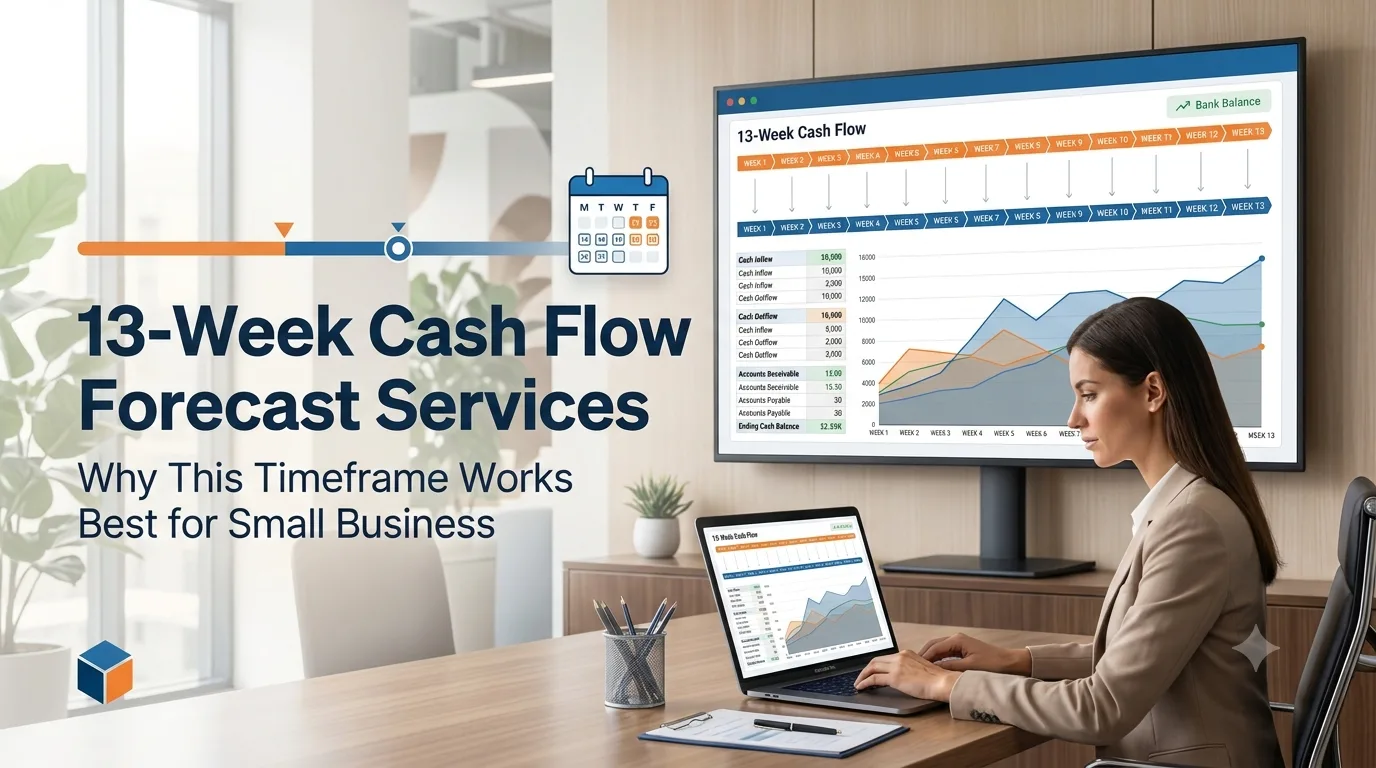
A 13-week forecast looks ahead at expected cash inflows and outflows week by week. The timeframe is long enough to reveal upcoming financial pressure but short enough to make the assumptions practical and actionable.
For many small businesses, that balance makes the 13-week period particularly useful.
What Is a 13-Week Cash Flow Forecast?
A 13-week cash flow forecast is a short-term financial model that estimates how a company's cash balance may change during the next 13 weeks.
The model generally starts with the business's current cash position. It then estimates expected cash coming in and cash going out during each week.
A simplified calculation looks like this:
Beginning Cash + Expected Inflows − Expected Outflows = Projected Ending Cash
The ending cash balance from one week becomes the starting point for the following week.
The forecast is usually updated regularly. As actual results replace estimates, another future week can be added to maintain a rolling 13-week view.
This is different from simply looking at a bank balance. The bank balance tells you what you have today. The forecast helps you understand what your cash position could look like several weeks from now.
Why 13 Weeks?
The value of the 13-week timeframe comes down to balance.
A forecast that looks only a few days ahead may not give management enough time to identify upcoming problems. A forecast covering several years may require assumptions that are too uncertain to be useful for immediate cash decisions.
Thirteen weeks sits between those extremes.
Three months of weekly information can capture several important business cycles, including:
- Payroll periods
- Customer collection cycles
- Vendor payment schedules
- Monthly operating expenses
- Tax payments
- Loan payments
- Seasonal changes
- Planned purchases
- Short-term financing needs
At the same time, the forecast remains close enough to the present that management can usually investigate individual assumptions.
Why Small Businesses Need Short-Term Cash Visibility
Large companies may have substantial cash reserves, multiple financing options, or dedicated treasury teams. Small businesses often have less room for unexpected timing problems.
A delayed customer payment can make a meaningful difference.
For example, imagine a business expects $80,000 from several customers during the next month. If those payments are delayed by three weeks, the business may suddenly need to cover payroll and supplier payments with less cash than expected.
The issue is not necessarily a lack of revenue. It is a cash timing problem.
Good cash flow forecasting for small business helps management see these timing differences before they create an immediate problem.
The Difference Between Profit and Cash
One of the most important lessons a small business owner can take from cash flow forecasting is that profit does not equal cash.
Suppose a company completes a $100,000 project and records the revenue. If the customer has 60-day payment terms, the company may not receive the $100,000 for another two months.
During that period, the company may still need to pay:
- Employees
- Contractors
- Suppliers
- Rent
- Insurance
- Taxes
- Loan obligations
The business may be profitable on paper while experiencing a cash shortage.
A 13-week forecast brings this timing issue into focus.
What Goes Into a 13-Week Forecast?
A useful forecast needs more than a starting bank balance.
Cash Inflows
Expected inflows can include:
- Customer collections
- Accounts receivable payments
- Deposits
- Financing proceeds
- Investment capital
- Tax refunds
- Other expected receipts
The important point is to estimate when the cash will arrive.
An outstanding invoice should not automatically be treated as immediate cash. Its expected collection date matters.
Cash Outflows
The model can also include:
- Payroll
- Vendor payments
- Rent
- Utilities
- Insurance
- Taxes
- Debt payments
- Inventory purchases
- Equipment purchases
- Contractor payments
- Other operating expenses
Separating recurring expenses from one-time payments can make the forecast easier to analyze.
The Role of Accounts Receivable
Accounts receivable can have a major effect on a small business's cash position.
A company may have $200,000 in outstanding invoices, but that does not necessarily mean $200,000 will arrive within the next few weeks.
A useful forecast considers factors such as:
- Invoice due dates
- Customer payment history
- Aging reports
- Current collection activity
- Known payment commitments
- Customers with a history of late payments
This makes accounts receivable forecasting more realistic.
If a major customer normally pays 15 days late, assuming payment exactly on the invoice due date may make the forecast look stronger than the actual cash position.
Accounts Payable Matters Too
The same principle applies to money going out.
A business may have $100,000 in accounts payable, but those obligations may have different due dates.
Some payments may be due next week. Others may not be due for 30 or 60 days.
A 13-week model organizes these obligations according to their expected payment timing.
This can help management understand where cash pressure is likely to occur and whether certain payment schedules need attention.
Why Weekly Detail Is More Useful Than Monthly Detail
Monthly forecasts can provide useful information, but they can sometimes hide short-term cash pressure.
Imagine a business starts a month with $100,000, receives $200,000 during the month, and pays $250,000 in expenses.
A monthly view might show a $50,000 reduction in cash.
But what if most of the $200,000 in collections arrive during the final week while payroll and vendor payments occur during the first two weeks?
The business could face a temporary cash shortage even though the month-end numbers appear manageable.
Weekly forecasting makes these timing differences easier to see.
13-Week Forecasting and Seasonal Businesses
Seasonality can make cash planning more difficult.
A business might experience strong sales during certain months and slower collections during others. Expenses may not decline at the same rate.
For example, a seasonal business could spend heavily on inventory several weeks before its busiest selling period. The forecast can show how that inventory investment affects cash before the expected sales arrive.
This is where cash flow scenario planning can add additional value.
Management can model different sales or collection assumptions and see how each scenario could affect the cash balance.
Using Scenarios Instead of One Prediction
A forecast should not be treated as a perfect prediction.
Business conditions change. Customers delay payments. Expenses increase. Sales forecasts can be wrong.
Instead of relying on one outcome, businesses can create several scenarios.
A basic structure might include:
Base Case: Expected collections and expenses occur roughly as planned.
Conservative Case: Collections are slower and certain expenses are higher.
Growth Case: Revenue increases, but the business also needs additional inventory, employees, or operating expenses.
This approach helps owners understand how much financial flexibility they have.
How the Forecast Supports Better Decisions
The purpose of a forecast is not to create another spreadsheet that nobody uses.
Its real value comes from supporting decisions.
For example, if the forecast shows that cash could become tight six weeks from now, management has time to investigate possible solutions.
Depending on the situation, those options might include:
- Improving customer collections
- Adjusting purchasing
- Reviewing discretionary expenses
- Negotiating vendor payment terms
- Delaying a nonessential purchase
- Arranging financing
- Revising hiring plans
- Building additional cash reserves
The appropriate response depends on the business. The forecast simply provides earlier visibility.
How 13-Week Forecasting Works With an Annual Budget
A 13-week forecast does not have to replace an annual budget.
The two tools serve different purposes.
An annual budget provides a longer-term view of expected revenue, expenses, profitability, and investments.
The 13-week forecast focuses on near-term cash availability.
For example, an annual budget may show that a business plans to purchase $100,000 of equipment this year. The 13-week forecast can help determine whether the company will have enough cash during the specific period when the purchase is expected.
This is one reason businesses can benefit from using both SMB budgeting and variance reporting and rolling cash flow forecasting.
The Importance of Updating the Forecast
A forecast becomes less useful when it is prepared once and forgotten.
Small businesses should compare actual results with projected results regularly.
If a customer was expected to pay $40,000 in Week 5 but does not pay until Week 7, the model should reflect that change.
If a planned expense is higher than expected, that should also be incorporated.
Over time, these comparisons can improve the assumptions used in the forecast.
The process becomes:
Forecast → Compare → Update → Reforecast
That cycle is more useful than treating the original projection as fixed.
What Financial Reports Support the Model?
A 13-week forecast works best when it is supported by reliable accounting information.
Useful inputs can include:
- Current bank balances
- Accounts receivable aging
- Accounts payable aging
- Payroll schedules
- Debt schedules
- Recurring expense information
- Recent financial statements
- Sales forecasts
- Known capital expenditures
- Tax payment schedules
Accurate bookkeeping also matters. If the underlying accounting records are incomplete or outdated, management may spend more time correcting the information than using it for planning.
When Should a Small Business Consider a 13-Week Forecast?
Not every small business needs a highly detailed cash flow model at all times.
However, it can become particularly useful when a company is:
- Experiencing rapid growth
- Dealing with uneven customer collections
- Managing seasonal revenue
- Taking on debt
- Preparing for a major purchase
- Expanding into a new location
- Managing tight working capital
- Preparing for financing
- Experiencing financial uncertainty
Businesses facing these circumstances may benefit from having a clearer view of their upcoming cash requirements.
What Makes a Forecast Useful?
The usefulness of 13-Week Cash Flow Forecast Services does not come simply from having 13 columns in a spreadsheet.
The assumptions behind the numbers matter.
A good forecast should be:
Current: Based on recent financial information.
Specific: Focused on actual expected receipts and payments.
Realistic: Based on reasonable collection and expense assumptions.
Flexible: Easy to update when circumstances change.
Actionable: Clear enough to support business decisions.
A complicated model is not necessarily a better model. For many small businesses, clarity and consistency matter more than unnecessary complexity.
How Cube Accounting Solutions Can Help
Cube Accounting Solutions provides accounting, tax, and Fractional CFO services for businesses that need practical financial support.
Cash flow forecasting can work alongside services such as budgeting, variance analysis, financial reporting, and KPI management. The goal is to turn accounting information into something business owners can use for planning and decision-making.
For a small business dealing with changing cash needs, a rolling 13-week forecast can become one part of a broader financial management process rather than a standalone spreadsheet.
Final Thoughts
The 13-week timeframe works because it provides a useful balance between detail and uncertainty.
Looking only a few days ahead may not provide enough warning. Looking too far into the future can require assumptions that become increasingly difficult to validate.
Thirteen weeks provides enough visibility to identify upcoming collections, payments, financing needs, seasonal changes, and potential cash shortfalls while keeping the forecast close enough to the present to remain actionable.
That is the practical value behind 13-Week Cash Flow Forecast Services.
For small businesses, the goal is not to predict the future perfectly. It is to understand the next several weeks well enough to make better financial decisions before cash problems become urgent.